What’s the Maximum Loan Amount Mentioned for Diamond Banc Coral Gables?
The maximum loan amount mentioned for Diamond Banc Coral Gables is $250,000. That figure can be useful to know if you’re considering a high value watch loan, but it is not the same as a guaranteed offer. The amount a borrower may qualify for can depend on the watch, its condition and documentation, the lender’s current criteria, and the final valuation.
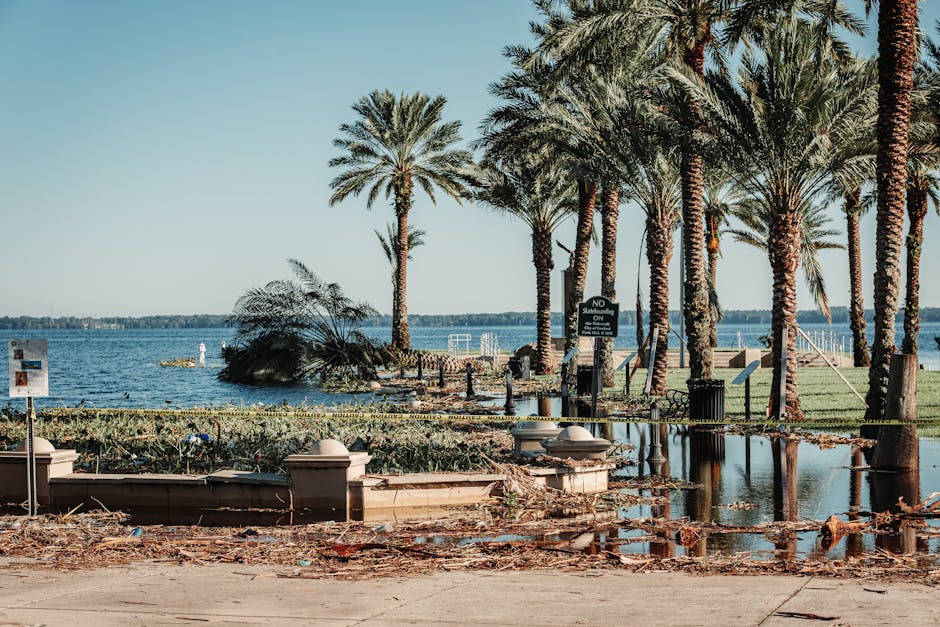
For South Florida homeowners, the question may come up at a particularly stressful time: after a hurricane. A damaged roof, water intrusion, or other covered loss can leave a household facing a large deductible and repair bills before insurance money arrives. In that situation, a loan secured by a watch may be one possible source of short-term liquidity. It is important, though, to understand both the insurance math and the loan terms before relying on it.
What the $250,000 Figure Does—and Doesn’t—Tell You
The $250,000 max loan figure is best treated as a stated upper limit, not a promise that every applicant can borrow that amount. A loan secured by a valuable watch is generally tied to the lender’s assessment of the collateral and its own underwriting rules. A watch’s retail price, insurance schedule, or owner’s estimate does not necessarily determine how much a lender will advance.
Diamond Banc is one company associated with collateral lending on luxury watches. In a collateral loan (watch held as security), the watch is pledged to secure the borrowing. Before proceeding, a borrower should ask how the watch will be evaluated, where and how it will be stored, what fees and interest apply, how repayment works, and what happens if payments are late or the loan is not repaid.
Those questions matter as much as the headline amount. A high borrowing limit does not establish the loan’s total cost, and it does not mean that borrowing up to that limit is financially sensible. Compare the written terms with other available sources of dwelling coverage deductible funds, and borrow only what you can realistically repay.
Why a Hurricane Deductible Can Create a Cash Gap
Florida homeowners’ hurricane deductibles are usually percentage-based rather than a simple fixed dollar amount. The percentage is generally applied to the insured dwelling limit shown in the policy, not to the amount of damage. The exact policy language and applicable rules matter, so homeowners should check their declarations page and confirm the calculation with their insurer or agent.
Common hurricane deductible options: 2%, 5%, 10%
Hurricane deductible Example on a $500,000 dwelling limit 2% $10,000 5% $25,000 10% $50,000These figures are examples, not a reading of any particular policy. They show why deductible math can create a five-figure cash gap. A homeowner with a $500,000 dwelling limit and a 5% hurricane deductible could be responsible for $25,000 before the insurer contributes toward covered damage, subject to the policy terms and claim facts. A 10% deductible on the same limit would be $50,000.
There may also be costs that are not covered, costs above policy limits, or expenses that must be paid before reimbursement. Even when a claim is covered, the timing and amount of payments can depend on documentation, inspections, estimates, and the policy’s terms. The deductible is only one part of the household’s potential out-of-pocket burden.
Why Cash Can Be Harder to Get After a Storm
In ordinary circumstances, a homeowner might consider savings, a home equity line of credit (HELOC), a personal loan, or a temporary loan secured by an asset. After a major storm, however, many people need money at the same time. Banks may face unusually high demand, and contractors may require deposits or prompt payment as they manage a surge in repairs.
That timing mismatch can make post-storm liquidity difficult. A family may need to pay for temporary housing, water mitigation, roof protection, or a contractor while waiting for claim decisions and insurance payments. The pressure is Click here not necessarily a sign that the household made a bad financial plan; it can reflect the practical gap between an urgent expense and a slower reimbursement process.
HELOCs and new credit can also be slow or paused after disasters. Lenders may change their procedures, require additional property information, or limit new lending in affected areas. A HELOC application that seems like a dependable fallback before a storm may not provide immediate access to funds afterward. It is worth asking a lender in advance about eligibility, timelines, and what could affect access to credit, rather than assuming a line will be available when needed.

Where a Watch-Secured Loan May Fit
A high value watch loan may be considered by an owner who has a suitable watch and needs funds without selling it outright. With a collateral loan, the watch is held as security during the loan term. That structure can be different from an unsecured personal loan, but it is not automatically cheaper, safer, or more flexible. The borrower is putting a valuable personal asset at risk if repayment obligations are not met.
Before using this option for storm-related expenses, compare the expected timing and cost with other choices. Ask for the annual percentage rate or a clear explanation of the interest calculation, any origination or storage charges, the payment schedule, and the consequences of default. Confirm the loan term and whether early repayment is allowed without a penalty. Get every material term in writing.
Also consider how much cash is actually needed. A loan sized to cover a deductible and immediate mitigation costs may be more manageable than borrowing the maximum available. Keep room in the household budget for ongoing mortgage payments, insurance premiums, utilities, and any uncovered repair expenses.
Using WatchCharts and Other Valuation Information
Before discussing a loan, an owner may want to understand the watch’s likely market range. Secondary market pricing trackers (WatchCharts) can help provide context by showing market information for certain watch models. That information can be a starting point for research, not a lender’s offer or a formal appraisal.
Secondary-market prices can vary by model, reference, condition, completeness, provenance, and current demand. A price tracker may not account for every detail of an individual watch, and a lender may apply its own valuation approach. Keep relevant records together, including purchase documentation, service history, certificates, box and accessories, and clear photographs. Do not assume that a quoted market price will translate directly into an equal loan amount.
Similarly, a relationship with a wealth manager or a firm such as Morgan Stanley does not by itself determine whether a watch loan is appropriate. A financial professional can help place borrowing in the context of a wider plan, but the lender’s actual contract controls the loan. Consider the full picture: cash reserves, insurance coverage, existing debt, income stability, and repayment capacity.
Questions to Ask Before Borrowing
If you are comparing a Diamond Banc Coral Gables offer with other funding options, use a consistent checklist. The headline maximum is only one data point. Ask:
- Is the $250,000 maximum available for my type of collateral and situation, or is it a general upper limit?
- How is the watch evaluated, and can I receive the valuation and loan offer in writing?
- Where will the watch be kept, and what protections apply while it is held?
- What is the total cost of borrowing, including interest and all fees?
- When are payments due, and what happens if I miss one?
- Can I repay early, and are there additional charges?
- What happens to the watch if I cannot repay the loan?
- How soon can funds be delivered after approval?
It is also sensible to compare the offer with alternatives, while recognizing that alternatives may not be available quickly after a disaster. Review savings, existing credit, a HELOC if already open, payment arrangements with contractors, and any insurance advance or reimbursement process available under your policy. A new loan should solve a defined cash-flow problem, not create a larger one.
Prepare Before the Next Storm
The most useful time to understand a hurricane deductible is before a storm is approaching. Find the deductible on your policy, calculate its dollar amount using the relevant dwelling limit, and set aside a reserve if possible. Keep policy documents and key contact information somewhere accessible, and maintain an inventory of valuables and household property.
For an expensive watch, retain ownership records and current photographs in a secure location. If you are considering borrowing against it, review potential lenders and their terms in advance rather than making a rushed decision while managing property damage. Planning cannot prevent delays or guarantee that credit will be available, but it can make the choices easier to assess under pressure.
The Bottom Line
The maximum loan amount mentioned for Diamond Banc Coral Gables is $250,000. Treat that as a stated ceiling—not a guaranteed approval, valuation, or recommendation to borrow that much. A watch-secured loan may offer one possible source of liquidity, but the watch serves as collateral and the costs and risks need careful review.
For Florida homeowners, the broader issue is often timing. Percentage-based hurricane deductibles can mean tens of thousands of dollars in potential out-of-pocket costs, while contractors and lenders may be stretched after a storm. Knowing your deductible, building a cash reserve, and understanding funding options before disaster season can help you make a calmer, more informed decision if repairs and insurance payments do not arrive on the same schedule.
This article is general information, not insurance, legal, tax, or financial advice. Policy terms, loan availability, pricing, and eligibility vary. Check your policy and review any loan agreement carefully before signing.